You may be ready for a yard, a garage, or a quieter place to work. The next buyer may be looking for exactly what you are leaving: a smaller footprint, a familiar block, or a city routine they can reach on foot.
That is the first distinction to make when preparing the sale. Your home has not stopped working because it no longer works for you.
Sell the city home on its own merits, then connect the sale to your suburban move without making either transaction depend on wishful thinking. The objective is not just a strong offer. It is the right combination of proceeds, usable dates, and flexibility.
This is the selling side of the transition. The companion Urban-to-Suburban Buying Guide helps you test whether the next location and home deliver the life you are moving for.
Define What the Sale Needs to Do
Before setting a launch date, identify the result the household needs. How much cash must the sale release? When must it be available? What is the latest workable move-out date? Which of those requirements can change?
Separate a preference from a hard limit. Wanting to move once is understandable. Requiring one perfectly synchronized move can become expensive when the search, financing, or buyer's schedule does not cooperate.
Work with representation appropriately licensed for each transaction. A D.C. sale and a Maryland purchase cross jurisdictions; paperwork, taxes, disclosures, and tenant issues need the right local review. Agree on who coordinates the overall plan and who is responsible for each contract.
Use the buying guide's keep, add, and stop exercise before spending heavily on listing preparation. There is little value in accelerating a sale around a destination the household has not actually agreed on.
Work From Net Proceeds, Not an Equity Headline
An estimated value minus a mortgage balance is not the same as cash available for the next purchase.
Build a transaction-specific net sheet that accounts for mortgage and other lien payoffs, agreed selling expenses, taxes and settlement charges, credits, adjustments, and any amounts paid or withheld from the proceeds. Track preparation and moving costs separately when they are paid before closing so they do not disappear—or get counted twice.
The CFPB explains that a payoff quote differs from a current balance: it includes interest through the payoff date and may include other unpaid charges. Request actual payoff figures for the relevant dates.
Use the compensation agreed in your listing agreement, not an assumed industry percentage. NAR's listing-agreement guidance states that agent compensation is negotiable and not set by law.
Then test the net sheet under different supported sale-price, concession, and timing assumptions. These are planning scenarios, not probability forecasts. Decide what happens to the next-home budget when the less comfortable scenario occurs.
Price the City Home in Its Own Market
The price of the suburban home you want is not evidence of what a buyer should pay for the home you own.
Ask for comparable sales and competing listings that reflect the actual property: condominium or rowhouse, building or block, layout, light, outdoor space, parking rights, condition, and ongoing charges. A nearby sale with a different ownership arrangement may not be the comparison it first appears to be.
Look at what the evidence supports and where judgment remains. Agree in advance on how showing feedback, competing inventory, and offers will inform a review of the strategy. Neither an automatic price cut after an arbitrary number of days nor an indefinite commitment to the original asking price is much of a plan.
You are participating in two markets, not one. Research the city sale and suburban purchase independently, then make their budgets work together. Optimism about one should not cover a gap in the other.
Choose the Sequence Before the First Offer Arrives
The Housecats Move-Up Seller Roadmap uses three pathways: Buy First, Then Sell; Sell First, Then Buy; and List & Shop Simultaneously. For a city-to-suburb move, choose among them using the cash available before closing, the flexibility of the household, and the evidence from the next-home search.
Buy First, Then Sell
This can create room to move out and present the city home without the household living through showings. It also places more weight on your ability to fund the purchase and carry the old property until the sale closes.
Ask the lender to evaluate that exact arrangement. Budget overlap and a slower sale, not just the ideal sequence. A bridge loan or home-equity borrowing is an additional financing obligation, not a guarantee about the eventual sale.
Sell First, Then Buy
This puts the sale ahead of the purchase. You can learn the suburban market before the listing launches; selling first does not require waiting until the city closing to begin your research.
Be precise about what has happened. An accepted offer begins the closing process. It does not finish the sale or make the proceeds available. If you commit to the next purchase while the sale is still pending, have your lender and advisers explain the remaining dependencies.
Discuss temporary housing and a negotiated post-closing stay as alternatives, not arrangements you assume the buyer must provide.
List & Shop Simultaneously
This lets preparation and the search advance together. It does not mean the two transactions will complete together automatically.
Use clear decision points: when the city home is ready, what sale terms would let you proceed, which funds support the next deposit, and how you will handle a home that appears before the sale is sufficiently secure. The buying guide's transition-financing check belongs beside this plan.
Qualifying Without the Old Payment Does Not Eliminate the Old Payment
Fannie Mae's pending-sale guidance generally counts both housing payments when the current residence will not close before the new purchase. It allows exclusion of the current payment from qualifying with an executed sales contract and confirmation that financing contingencies have cleared.
That is an underwriting rule for covered loans—not release from the old mortgage, receipt of the proceeds, or assurance the sale cannot fail. Ask your lender which rules and additional requirements apply, and keep the actual carrying cost in the household plan.
Prepare a City Property File Before You Prepare the Launch
A useful file answers the questions that photographs cannot. Assemble permits and improvement records, relevant warranties, disclosures, title or ownership information, and documentation for features you intend to market.
For a Condominium or Cooperative
Request the appropriate resale and management documents early. Review budgets, reserves, meeting minutes, insurance, assessments, significant planned work, litigation, transfer procedures, and the requirements for showings and moves.
The building can matter to the buyer's financing even when the unit itself is in excellent condition. Fannie Mae identifies certain condo and co-op projects needing critical repairs as ineligible and requires lenders to investigate relevant assessments and reports. Routine work and critical repairs are not the same classification.
Ask the management company and lender for the actual review rather than declaring a building eligible or ineligible from a rumor. Good records cannot cure a problem, but they can help the parties identify it before the move depends on a closing date.
For a Rowhouse or Other City Home
Establish the evidence behind roof-deck work, additions, basement alterations, shared access, and any claimed rental space. Have title and inspection professionals investigate the relevant rights and condition issues.
Be exact about parking. A deeded space, an assigned space, a separately leased space, and eligibility to apply for street parking are different claims. Describe only the arrangement the documents and responsible authority support.
Ask about ground rent when relevant to a Maryland property. SDAT's registry is a research resource, not a title determination. The title review should establish the actual interest and obligations being transferred.
When Someone Else Lives There
Have local counsel review the tenancy before promising vacancy, a showing schedule, or a closing date. In D.C., TOPA and related notice requirements include exemptions and retained protections. An exempt property does not automatically mean there is no notice or tenancy issue to resolve.
Give the attorney the leases and occupancy history. Coordinate lawful access and any agreed transition respectfully. Do not treat selling the property as its own authorization to end someone's tenancy.
Prepare for the Next Owner, Not for Your Next Home
Keep the preparation list tied to the home's current competitive position. Address material condition questions, make the rooms easier to understand, clean thoroughly, and decide which modest repairs or presentation changes are worth doing.
A small bedroom may make more sense with appropriately scaled furniture than with a renovation. An entry might need better lighting and less storage in the way, not a new architectural concept. Investigate a recurring leak rather than paint over the evidence before photography.
Put a scope, budget, responsible person, and completion date beside each approved task. Preserve enough cash for the next deposit and the move. The goal is not to renovate the city home into a version of the suburban one you are buying.
Have your agent explain applicable disclosure duties and how new findings should be handled. Presentation should make the property easier to evaluate—not conceal something the buyer needs to know.
Market the Life Someone Can Have There
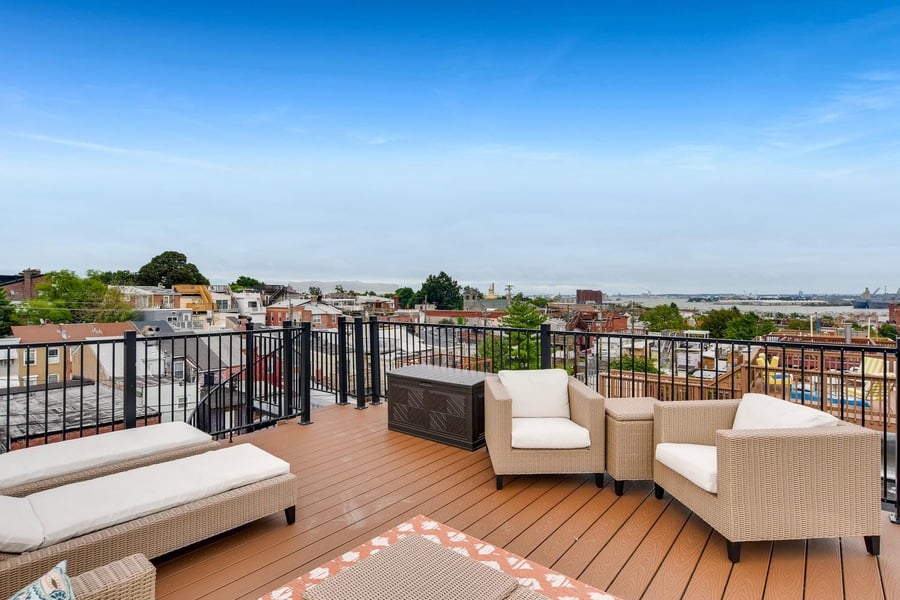
Build the story around supported features: a useful floor plan, light, storage, an outdoor terrace, the actual parking arrangement, and the routes to places a buyer may use. Include accurate photographs and a clear floor plan. Show the approach and shared spaces when appropriate and authorized.
Describe the home's function without deciding which kind of person belongs there. A room can serve as an office or guest room; the marketing does not need to label the property for a protected demographic.
Do not advertise your own dissatisfaction. Wanting a lawn does not make a roof terrace a compromise to everyone. Someone else's next chapter may begin with the city life you have enjoyed.
Your reason to leave is not the home's sales pitch.
Evaluate the Whole Offer Against the Move
Compare price with credits, financing, appraisal provisions, inspection terms, deposit arrangements, contingencies, closing date, and possession. Have the listing agent examine how each term affects the sale and your next obligation.
A larger deposit does not automatically become money you can spend or keep. A cash offer still needs appropriate verification and contract review. A fast proposed closing is helpful only when it is supported and fits your plan.
As a decision test, compare a concession with the additional carrying cost or disruption an alternative would create. That is not a rule to accept a lower price; it is a reason to calculate the effect instead of negotiating one line in isolation.
Keep objective criteria and your priorities written down. A desire to buy a particular suburban home should not turn an unworkable city offer into an acceptable one.
A Rent-Back Needs More Than a Move-Out Date
A negotiated stay after the sale can help align the move, but it depends on agreement and the buyer's financing and insurance requirements. Have the parties' advisers review the proposed occupancy before relying on it.
Document the period, payment, deposit or escrow arrangement, utilities, maintenance, damage responsibility, access, insurance, final inspection, and what happens if possession is not delivered on time. Do not assume a standard form answers every circumstance.
Compare that arrangement with temporary housing. Moving twice can be inconvenient; an open-ended possession promise can create a much larger problem. Keep a fallback that works even if your preferred suburban home is not ready.
Keep Three Clocks on One Calendar
The commitment clock: when offers become binding, protections expire, deposits are due, and notices must be delivered.
The cash clock: when money must leave your account, when each loan can fund, and when the settlement team confirms sale proceeds can be disbursed and used.
The possession clock: when you must leave one property and are entitled to enter the other.
A matching date on two contracts does not establish that those clocks align. Ask the settlement professionals about funding, disbursement, wire cutoffs, and the sequence they can actually support. Ask counsel how one contract responds if the other transaction is delayed; do not assume they protect each other automatically.
Book the mover, elevator, loading space, and services around confirmed arrangements, with the cost of changing them understood. Keep access, deliveries, pets, work commitments, and essential records in the plan.
If the destination remains uncertain, return to the buying guide's rent-first comparison instead of making a permanent purchase simply to rescue a temporary deadline.
Keeping the City Home Is a Separate Investment Decision
“We could always rent it” needs a real operating plan: permitted use, lease and licensing requirements, insurance, management, maintenance, vacancy, reserves, and lender treatment. Evaluate supported rent and actual costs rather than assume rent will cover everything.
Taxable gain is not the same number as cash left after paying off the mortgage. IRS Publication 523 explains the basis, gain, ownership, use, and other tests involved in selling a main home. Rental history and depreciation can affect the result.
Review a proposed rental period and eventual sale with your tax adviser before changing the property's use. Do not treat buying another home as an automatic exemption from tax on the first one.
Finish the Sale With Options Intact
Keep watching three things as the move progresses: the actual response to the city listing, the availability and suitability of the suburban alternatives, and the conditions still outstanding on each transaction.
When one changes, update the budget and calendar together. Do not let a listing date become more important than readiness or a desired move date become a reason to disregard a material risk.
The strongest transition is not necessarily the one with the fewest days between keys. It is the one where you understand what you are committing to, have the money when you need it, and retain a workable alternative if the preferred sequence changes.
Call (410) 991-1382 to plan the sale and your next move together. Start with the outcome, then organize the two transactions around it.
Research reviewed September 22, 2026. This is general selling and transition information, not individualized legal, tax, lending, or investment advice. D.C. and Maryland requirements differ; use appropriately licensed representation and jurisdiction-specific professional review. Financing criteria depend on the loan and lender. Housecats library photographs are illustrative and do not establish a property's location, condition, legal rights, or current availability.